Wednesday, July 20, 2011

What can you do for me?

I was visiting with a prospective client the other day, and they asked me a very interesting question:

“What can you do for me that I’m not already getting from my current agent?”

Now THAT’S the million dollar question! To be honest with you, I spent the first 10 years of my insurance not really able to answer that question with an effective response. Some of my stammering included:

---“Because I am very knowledgeable”

---“I have 10 years experience”

---“My winning personality!”

---We give the best service (what does that really mean?)

The last few years, I have been more focused on helping the customer find ways to reduce their risks in their business through focusing on their operation and creating more knowledge and awareness of claims management in their organization. I have found that it’s not the truck that causes a wreck, not the building that causes liability, and not the job function that causes an employee to get injured- it’s the people in your organization that cause the claims!

I have spent the last 4-5 years trying to help my customers create a better working environment for their employees, as well as setting expectations for those employees. Some insureds are better than others at taking experienced advice. Those customers have seen tremendous results in their risk management programs- others not so much.

Back to original question: “What can you do for me that I’m not already getting from my current agent?” Let me answer that question-

“We have been very successful at helping you the business owner or manager find new and innovative ways to run your business more effectively with fewer claims and better response to the claims you do have. In short, we can make your company more profitable in the long run than our competition. I feel extremely confident about that fact.”

What about your business? What can you do for your customers that they are not already getting from a competitor? Let me know your thoughts to this question.

Bobby Bland PWCA, CIC
Vice President
Commercial Risk Service

Thursday, July 14, 2011

Confessions of a Food-aholic

Many times in life, we tend to make up rules as we go, such as:

---“If you cross your eyes too many times, you could end up that way permanently.”

---“It’s OK to tell your mother a little white lie, as long as it “makes her feel better.” (or as you get older, maybe a little bigger lie!)

---“Don’t remove this tag under penalty of law”. (I wish I would have thought of that!)

---“If you do something wrong, it will go on your permanent record.” (where do they keep that “permanent record?”

…or we make up our minds about our own personal limitations, such as…

---“My brother got the brains in our family, so I guess I’m just a screw-up.”

---“I would never be able to make it through college because our family doesn’t have the money.”

---I am not really fat, just “big boned”! ( Or I heard this one- “I can carry more weight because I’m long-waisted!.”

As a child, I always loved being the biggest kid in school. I was WAY bigger than everyone else my age- taller, bigger, and stronger- the fat part came later. Along with that came the fact that I ate more- my parents always told me “eat as much of meat and potatoes as you want, and drink all the milk you want, and it will make you bigger and stronger” (another questionable rule!). So I did- I ate steak and potatoes and all the trimmings every meal, along with about 7 gallons of whole milk per week.

When I got into adulthood, I still ate a lot of food, even though I was obviously through growing taller, just wider. I always told myself that “I was just a bigger person than everyone else, and I needed more food to maintain”. Everyone always told me “You’re not really fat, just big boned.” Somebody even once told me that “You’re not overweight, you’re just under-tall!”

Fast forward to February of this year: I had been diagnosed at a Type II Diabetic about 5 years ago, having to take insulin for the high blood sugar, medication for high blood pressure and high cholesterol. In addition, I had been diagnosed 5 years ago with sleep apnea because of my morbid obesity and was using a C-PAP machine to help control that at night when I slept. I had lost 50 pounds 3-4 years ago (down from 390) to now weigh 340 pounds, but couldn’t get any more weight off because the insulin makes you gain weight.

I decided to make a last-ditch effort to change my life and had gastric bypass surgery on February 1st this year. In the 5 ½ months that have followed, not only have I lost 120 lbs., to now weigh 220, I also no longer take any medications! I don’t have to use Insulin because my blood sugars are now normal. I am completely off high blood pressure medications, high cholesterol prescriptions. I now work out 90 minutes EVERY DAY.

Even better, I have also lost a lifetime of pre-conceived ideas that have held me back all these years:

---I am not doomed to be “big and fat” all my life”. I can choose to be the size and shape I want to be.

---My knees (which I have had 5 surgeries on) don’t have to hurt all the time. I can now walk 7-8 miles hard and have no pain.

---I no longer believe that if I work out 3 times per week, I can improve my health, because I am dedicated to working out EVERY DAY, no matter what.

---I also am saving about $500-$700 every month simply because I no longer feel that I need to eat out at a restaurant every meal. (I can even drive by a Zaxby’s without pulling in!)

My point is this…

You can be anything you make up your mind to be. If you choose to be fat, you will be fat. If you choose to be unhappy, you will be miserable. If you choose to keep your business (or your career) in the same mediocrity it is in today, you will be stuck with that mode forever. Instead, decide to change your life and your business for the better. Take the limitations off of yourself, and go accomplish something! Get excited about what you are doing in your life, even if it means changing your life completely.

Give me some feedback and tell me what you want to change in your life or your business today.

Bobby Bland PWCA, CIC
Vice President
Commercial Risk Service

Wednesday, July 13, 2011

Americans Keep Getting Fatter, Especially in the South

Los Angeles—In 1995, no state had an obesity rate above 20 percent. Now, all but one does.


An annual obesity report by two public health groups looked for the first time at state-by-state statistics over the last two decades. The number of obese U.S. adults rose in 16 states in the last year, helping to push obesity rates in a dozen states above 30 percent, according to a recently released report.

Mississippi is the fattest state in the union with an adult obesity rate of 34.4 percent. Colorado is the least obese—with a rate of only 19.8 percent—and the only state with an adult obesity rate below 20 percent, according to “F as in Fat,” an annual report from the Trust for America’s Health and the Robert Wood Johnson Foundation.

“When you look at it year by year, the changes are incremental,” says Jeffrey Levi, executive director of the Trust for America’s Health, which writes the annual report with the Robert Woods Johnson Foundation. “When you look at it by a generation you see how we get into this problem.”

Obesity rates did not decline in any state and even Colorado does not win high marks—it’s score means one in five state residents is at a higher risk for conditions like heart disease and diabetes.

“Today, the state with the lowest adult obesity rate would have the highest rate in 1995,” said Levi.

Four years ago, only one U.S. state had an adult obesity rate above 30 percent, according to the report. Obesity is defined as a body mass index – the weight to height ratio – of 30 or more.

The study, based on 2010 data, says a dozen states top the 30 percent obesity, most of them in the South. Mississippi topped the list for the seventh year in a row, with Alabama, West Virginia, Tennessee and Louisiana close behind. Just five years ago, in 2006, Mississippi was the only state above 30 percent.

Wednesday, July 6, 2011

Does a Marina need Flood Coverage?

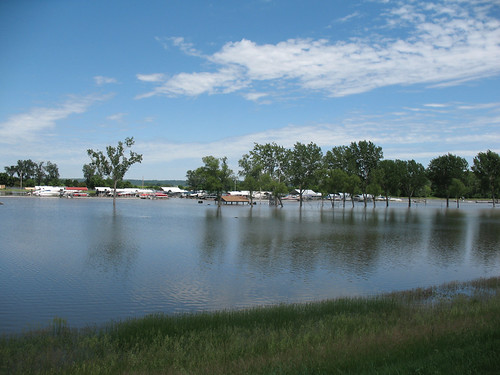
Most property policies exclude flood coverage for land-based property such as buildings. A flood policy can be purchased to cover the land property but unfortunately, due to the location of marinas in high hazard flood zones, the coverage can be very expensive. In addition, a flood policy has a 30-day delay before coverage takes effect. Do you need flood coverage for your land property? Have you experienced a major flood since you have owned your marina? If so, is any of your land property at risk if the lake floods to maximum elevation or even a couple of feet higher than the “top of flood pool”? A lake can definitely flood to heights above the “top of flood pool” if the conditions are right. I have personally experienced this on Beaver Lake. So, if any of your land property is at risk of flood damage, you should ask your agent for a flood quote to determine whether you wish to cover this peril with insurance.


Boat docks are typically covered under an inland marine “Piers, Wharves, and Docks” policy and flood is usually a covered peril under those types of policies and that coverage is in effect for the entire policy term, with no 30-day delay in coverage. There are a few insurance companies that will endorse a standard property policy to include dock coverage but those types of policies would exclude any dock damages due to flood. You need to check with your agent to confirm which type of coverage you have because a flood can damage dock walkways, electrical systems, fuel systems, winches/cabling, etc. If your policy covers flood damage to your docks, you may also have a loss of business income claim as well.

If you have, or are considering purchasing an insurance policy that excludes flood for your docks, ask yourself whether you are prepared for fast rising water, water current, and able to maintain access to your docks. If you have already experienced flood conditions, you have a pretty good idea what can happen to your docks, electrical system, and fuel system. Flood damage to docks is typically limited and due to the flood deductible, this exclusion may not be a huge issue to you. However, if you haven’t experienced a major flood, you may want to purchase a policy that will cover flood so that you don’t experience any financial loss due to a flood.

If you are unsure, you should discuss this issue with your agent.

Doug Timmons, CIC, CMIP
Marina Insurance Specialist
Commercial Risk Service

Thursday, June 30, 2011

Federal Appeals Court Rules Health Care Reform Bill is Constitutional

The political and legal future of Healthcare Reform received a big boost Wednesday after a federal appeals court in Cincinnati ruled in favor of the Obama administration and Congress, concluding a key provision in the landmark legislation was constitutional.

The “individual mandate” requiring all Americans to purchase health insurance by 2014 or face financial penalties—was challenged in federal courts by a large number of individuals and groups, who said people should not be forced to purchase a product like medical coverage. A partially divided U.S. Court of Appeals for the 6th Circuit disagreed.

“We find the minimum coverage provision is a valid exercise of legislative power by Congress under the Commerce Clause,” said the three-judge panel on Wednesday, in a 64-page opinion.

The opinion is the first of three rulings that will emerge from the federal appeals courts around the country in the coming weeks over the Patient Protection and Affordable Care Act.

The issue is almost certain to eventually reach the Supreme Court, perhaps by year’s end. More than two dozen other legal challenges to the law are floating in lower federal courts.

Email-"E" is for evidence

Do employees in your organization know how to send email? Of course they know how to physically send a message. But have you ever taught them what should- and, more importantly, should not- be included in emails?

The "E" in email stands for eternal evidence and it doesn't go away! Here are a couple of examples of real email mistakes that cost employers big in court, including managers who included these words in their email:
  • "We would like to accommodate you, but we're not set up for blind people." (an $8 Million verdict!)
  • "I don't care about the FMLA, shmeflma!" (a $650,000 verdict!)
  • "I'm sick of always have to accommodate her."
Corporate emails are a "treasure trove of evidence" in employment law court cases. More than 107 trillion emails were sent in 2010 alone and business people spend about 25% of their workdays on email. This constantly changing online environment is creating a legal minefield for U.S. employers. Employers are required to place a "litigation hold" on destroying any email once they become aware that a legal claim may be coming.

Think about it- how much training or time is spent with your middle management or upper management talking about the information that is contained in interoffice emails? Employees should have no expectation of privacy with emails- NONE! And you should make that perfectly clear with every employee- salaried or hourly. Here are 3 myths commonly held by employees concerning emails:
  1. It's my e-mail, with my name on it, so you can't search it.
Employer response: A simply stated email policy puts you on notice of the employer's rights and defeats your reasonable expectation of privacy.

  2.  It's my own personal password and personal folders, not the Company's.

Employers response: True, but they are being transmitted on the company's network, therefore, it is property of the employer.

   3. I own my own computer and bring it to work.

Employer response: The computer was being used for work-related purposes and therefore you have no reasonable expectation of privacy.

Employees need to realize that "they're always creating legal documents with the creation of each new email. HR should teach employees to approach email based on these three guiding principles"
  1. Start all emails by asking yourself, "Does this need to be in writing?" If not, pick up the phone or walk down the hall.
  2. If you can't say it in person, don't email it.
  3. Write every email like it's going to be read to a jury... because it just may be!
Comment back and let me know of any "mistakes" that you know have been made with your company emails, and how you solved the problems.

Bobby Bland PWCA, CIC
Vice President
Commercial Risk Service
Thursday, June 23, 2011

How to retain your best employees

The rules of employee retention have changed. No longer can loyalty be bought with big salaries, hefty bonuses, and rich benefits packages. Today it takes intangible, non-monetary rewards to creates an atmosphere that makes your people feel valued, respected, and involved. It takes a whole new way of thinking. This is the 20th and Final edition of a 20-week special on ideas you could implement to keep those best employees:

20) Hire the Right People
One surefire way to retain good people is to hire good people in the first place! Today, more than ever, the hiring process involves much more than reviewing qualifications, checking references, and negotiating salaries. In fact, many managers are learning that employees' intangibles may override their work experience. After all , new hires can always be trained in the nuances of your business. What's harder to teach, however, is compatibility with your current staff, positive attitude, and work ethic-all of the ingredients that make for a long-lasting employee-employer relationship.

As you meet with job applicants, be sure to schedule multiple interviews with the most promising candidates. Keep bringing them back until you have a good feel for their personalities, their likes and dislikes. It's better to uncover their good- and bad- qualities before they come on board.

Also make it a regular practice to invite current employees to attend interviews. They may know better than you how a new person will relate to the rest of the staff. And, you'll also send a clear message that their input is welcome, needed and valued.

I hope you have enjoyed this 20-week look into retaining your best employees. If you need any more information about this subject, please don't hesitate to contact me.

Bobby Bland PWCA, CIC
Vice President
Commercial Risk Service